


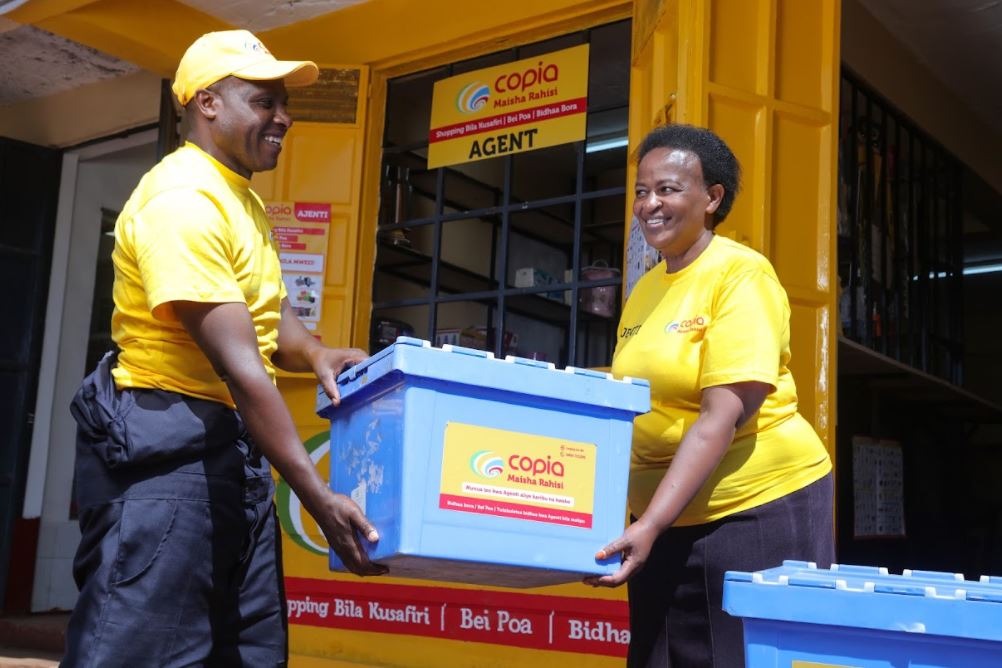
Copia Global arrived with the kind of story the modern investment world loves. It promised to use technology, mobile ordering and a network of local agents to bring household goods closer to underserved families, especially in rural Kenya. It attracted respected investors, expanded its operations and became one of the most recognisable names in Africa’s startup ecosystem. Over roughly 12 years, the business raised at least US$123 million, equivalent to about KSh15.8 billion at the exchange rate cited in later reporting. Then the money ran out, attempts to secure additional capital failed, the company entered administration in May 2024 and its Kenyan operations moved towards liquidation.
That sequence should stop us in our tracks. A company can fail; business has never offered anyone a guarantee. Innovation involves risk, and some ventures will collapse despite honest leadership and intelligent investors. But KSh15.8 billion is not pocket change. It is enough money to change entire value chains. When capital of that magnitude enters a company that ultimately cannot sustain itself, “the startup failed” is not a complete explanation. It is the beginning of the questions.
What did the investors believe they were buying? What did the board know about the company’s unit economics? How much did it cost to acquire and serve each customer? How much margin remained after storage, transport, agent commissions, failed deliveries, technology, management and administration? At what point did expansion stop creating value and start magnifying losses? Were warning signs confronted early, or did everyone remain loyal to the next fundraising round? Most importantly, what measurable productive capacity remained after the capital was consumed?

These questions are not accusations of theft. They are the ordinary questions that accountability demands. If anyone alleges that money was siphoned, that allegation must be supported by audited records, contracts, bank trails and findings from competent investigators. But the absence of proven wrongdoing does not remove the obligation to examine governance, incentives, spending discipline and investor oversight. A system can waste enormous amounts of money without a single dramatic suitcase of cash changing hands. It can happen through weak assumptions, expensive expansion, poor controls, fashionable strategies and the refusal to admit that a model is not working.
Capital raised is not revenue. Valuation is not profit. Expansion is not sustainability.
Kenya has gradually learnt to treat fundraising announcements like national victories. A startup raises ten million dollars and the headlines call it a success before it has produced a shilling of profit. Founders become celebrities. Valuations are repeated as though they were cash in the bank. Photographs of signing ceremonies travel farther than audited accounts. Meanwhile, the mechanic, miller, manufacturer, farmer, laboratory owner and school proprietor are asked for collateral, three years of statements, tax records and proof that every cent will return with interest.
This is the uncomfortable contradiction at the heart of our funding ecosystem. A conventional Kenyan enterprise may already have customers, machinery, employees and a visible product, yet struggle to borrow KSh10 million for a production line. A venture-backed company can present a promise of rapid scale, accept years of losses and raise billions because its story fits the appetite of global capital. One business is judged by cash flow. The other is often judged by growth, reach and the possibility of a future exit. We must ask whether that imbalance serves Kenya’s long-term economic interests.
The human cost is easily buried beneath corporate language. Administration, restructuring and liquidation sound clinical. In real life they mean an employee returning home to explain that the salary has stopped. They mean a supplier who delivered goods on credit and may never recover the full invoice. They mean an agent whose small commission kept children in school. They mean landlords, transporters and other small businesses absorbing losses created far above them. Investors may record an impairment in a portfolio. A Kenyan household experiences a crisis.
The Copia story therefore deserves more than gossip about founders or a celebration of failure as proof that entrepreneurs are bold. Kenya needs an independent, evidence-led introspection into its startup ecosystem. We need to examine how investment decisions are made, how boards supervise founders, how related-party spending is controlled, how executive compensation is determined, how expansion milestones are approved and how quickly investors intervene when the numbers stop making sense.
We should also question the culture of secrecy. Companies routinely publicise capital raised but rarely disclose the operating indicators that would allow the public to understand whether that capital is producing durable value. How many businesses disclose contribution margin by market, customer-retention costs, cash burn, debt obligations or a credible route to profitability? If a venture employs hundreds of people and affects thousands of suppliers and agents, transparency should not appear only after collapse.
What KSh15.8 Billion Could Build
Now consider the opportunity cost. KSh15.8 billion could provide KSh100 million in patient capital to 158 established enterprises. It could provide KSh20 million to 790 growing businesses. It could provide KSh10 million to 1,580 manufacturers, agro-processors, clinics, diagnostic centres, vocational institutions and other productive SMEs. These examples are illustrations, not a proposal to divide capital mechanically. Their purpose is to show the extraordinary scale of resources involved.
In manufacturing, that capital could finance production lines, packaging equipment, cold rooms, quality-control systems and energy-efficient machinery. The benefits would not end at the factory gate. A functioning plant buys raw materials, trains workers, supports transporters, pays utilities, creates demand for maintenance and keeps money circulating locally. It can substitute imports, earn foreign exchange and create skills that remain valuable even when one company changes ownership.
In agro-processing, billions could move farmers away from the humiliating cycle of producing abundantly and selling cheaply because there is nowhere to store or process their harvest. Kenya needs milk coolers, grain dryers, fruit pulping lines, animal-feed plants, edible-oil processors, abattoirs, warehouses and reliable rural logistics. These may not sound as fashionable as an app, but they reduce post-harvest losses, stabilise farm incomes and turn raw produce into products with longer shelf lives and higher value.
Healthcare and diagnostic medicine offer another urgent case. Many Kenyan families travel long distances, wait for days or pay unaffordable fees to access dependable tests. Patient capital could support regional laboratories, pathology capacity, imaging centres, oxygen plants, local manufacture of basic medical supplies and digital systems that connect clinicians to results. A well-run diagnostic centre does more than generate revenue. It shortens the distance between illness and treatment, and sometimes between life and death.
Education also needs serious investment, particularly technical and vocational training. Kenya cannot industrialise on motivational speeches alone. It requires electricians, machinists, food technologists, laboratory technicians, welders, plumbers, software engineers and production supervisors. Capital directed towards credible institutions could finance modern workshops, teaching laboratories, apprenticeship partnerships and affordable student financing. That investment would create the human capability on which manufacturing and healthcare depend.
Kenya does not suffer from a shortage of ideas. It suffers from capital that too often rewards the story before testing the economics.
Technology Must Serve Production
This is not an argument against technology or startups. Kenya’s future requires both. Technology can lower costs, connect markets, improve diagnosis, trace agricultural supply chains and make factories more productive. The mistake is treating technology as an economic sector floating above the physical world. The strongest innovation should help us manufacture more, process more food, deliver better healthcare, teach more effectively and export higher-value products.
We should stop forcing a false choice between the “old economy” and innovation. A modern dairy processor uses sensors, data, cold-chain software and digital payments. A diagnostic laboratory relies on information systems and automated equipment. A manufacturer uses computer-aided design, inventory platforms and predictive maintenance. These are technology businesses too, but their technology is anchored in production, skills and real demand.
The deeper policy question is what kind of risk Kenya is willing to subsidise. If patient capital can tolerate years of losses while a platform chases scale, why can it not offer a manufacturer a longer repayment period while machinery is installed and markets are developed? If investors can fund customer acquisition with no collateral, why can blended-finance institutions not support a proven agro-processor purchasing equipment? If billions can pursue an uncertain valuation, why is a functioning medical laboratory denied credit because its machines are considered difficult collateral?
Funding productive enterprises does not eliminate failure. Factories can be mismanaged. Schools can deliver poor outcomes. Hospitals can overcharge. Agro-processors can lose markets. Every sector requires due diligence, good governance and consequences for misconduct. The argument is not that traditional businesses are automatically virtuous. It is that Kenya should assess capital by the durable value it creates: jobs, skills, productive assets, healthier people, processed goods, export capacity and resilient local supply chains.
The Reckoning Kenya Needs
An honest review should begin with Copia’s audited financial history, cash-burn trajectory, governance structure and expansion decisions. Investors and administrators should explain, within legal limits, what failed and when it became clear. Former employees, agents, suppliers and creditors should be heard, not treated as footnotes. Regulators and policymakers should examine whether disclosure and insolvency rules adequately protect the smaller parties that absorb the harshest losses.
Development-finance institutions, venture funds, banks, pension funds and government agencies should then publish clearer measures of economic additionality. For every large investment, we should be able to ask: How many sustainable jobs were created? What local assets remain? How much domestic value was added? Were suppliers paid fairly and on time? Did the company develop Kenyan skills and leadership? Did it reduce imports, expand exports or solve a genuine social problem at a viable cost?
Founders also need a cultural reset. Raising money should be treated as accepting responsibility, not receiving applause. Investor capital is not evidence that a model works; it buys time to prove that it can work. Boards must reward honesty about bad numbers. Investors must stop encouraging reckless growth merely to make the next valuation possible. The ecosystem must make it respectable to slow down, repair unit economics and build a smaller profitable company rather than a celebrated giant that survives only while fresh money arrives.
Copia’s original mission was compelling because it spoke to a real Kenyan problem: serving consumers beyond the reach of conventional retail. Its collapse does not mean that rural commerce is unworthy of innovation. It means a worthy mission cannot rescue unsustainable economics. Good intentions do not pay suppliers. Impressive technology does not cancel logistics costs. Large funding rounds do not excuse weak discipline.
KSh15.8 billion came into one ambitious enterprise and the enterprise still failed. We should resist the lazy conclusions that all startups are fraudulent or that all founders are careless. But we must reject the equally lazy habit of calling every collapse an unavoidable experiment and moving on. When so much capital disappears, accountability is not hostility to innovation. It is how a serious economy learns.
Kenya must now decide what it wants its scarce capital to accomplish. We can continue financing stories designed mainly to impress the next investor, or we can build a system that values technology while also backing factories, farms, laboratories, hospitals, training institutions and productive SMEs. The country needs innovation, but it also needs machines that run, crops that are processed, diseases that are diagnosed, young people who are trained and businesses that remain standing after the applause has ended.
That is the lesson Copia should leave us with. The next billion-shilling announcement should not make us ask only who invested and at what valuation. We should ask what Kenya will own, what Kenyans will learn, how many livelihoods will endure and when the business will become capable of paying its own way. Until those questions become normal, we will keep celebrating money on the way in and mourning livelihoods when it disappears.
Read Also: Copia Global Hosts MIT Global Entrepreneurship Lab Project