


There is a particular confidence that arrives with a payment notification. For a few glorious minutes, life has possibilities. You can save, clear a debt and finally start that investment you have been discussing since January. Then rent clears its throat. School fees pull up a chair. A forgotten subscription quietly helps itself. By evening, your money has held a meeting and left without sharing the minutes.
You worked for that money. You sacrificed time, chased a customer, survived a difficult boss or opened your business before sunrise. Yet earning it can feel much easier to explain than what happened afterwards. That uncomfortable gap is exactly why financial literacy deserves a place in our lives, and why Serrari’s KES 750 Thursday evening webinar deserves serious consideration.
Many of us left school better prepared to pass an examination than to manage a payslip. We learnt percentages, but applying them to loan charges, investment fees and a household budget was often another story. Some people studied business or received excellent guidance at home. Many others entered adulthood with the instruction “work hard” and were expected to discover the rest while the bills were already arriving.

So we learnt through experience. Unfortunately, experience is a lecturer with expensive fees and a very unfriendly refund policy. The first lesson might be a loan whose repayment looked manageable until every other bill arrived. The next might be an investment recommended by someone whose main qualification was speaking with confidence. A financial education gives us a chance to ask better questions before paying for another painful lesson.
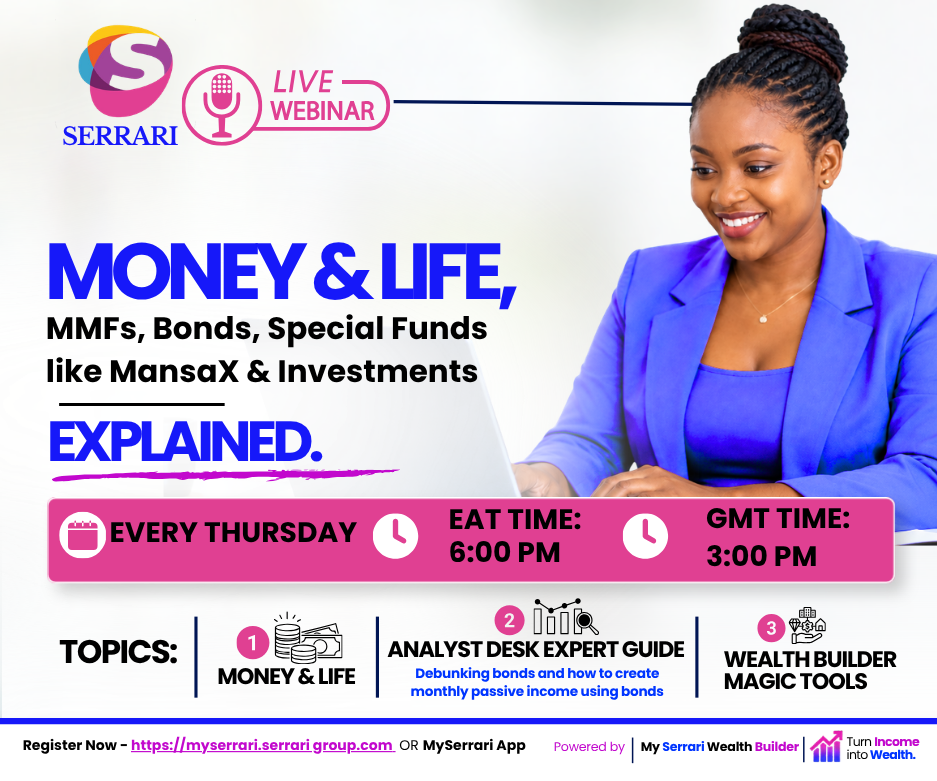
Serrari offers a practical starting point: a live webinar every Thursday at 6:00 p.m. East Africa Time, equivalent to 3:00 p.m. GMT, at KES 750 per session. Its advertised Money & Life series covers money market funds, bonds, special funds such as MansaX and investment concepts, alongside its Analyst Desk and Wealth Builder themes. These are subjects that can sound intimidating until someone explains the decisions behind the terminology. [7]
Kenya’s numbers show why the conversation matters. The 2024 FinAccess Household Survey reported formal financial access of 84.8%, yet only 18.3% of adults were classified as financially healthy. The survey was led by the Central Bank of Kenya with the Kenya National Bureau of Statistics and FSD Kenya. Access to an account or financial service is a major achievement, but it does not automatically translate into the ability to meet daily needs, withstand shocks and provide for tomorrow. [1]
The same survey found that 42.1% correctly answered all three financial-literacy questions covering inflation, interest rates and diversification. That is fewer than half. Those ideas affect ordinary life: how prices erode what savings can buy, how borrowing costs accumulate and why concentrating everything in one investment can leave you exposed. These are questions about protecting the money already passing through your hands. [1]
This knowledge gap extends beyond Kenya. In the OECD’s 2023 survey covering 39 countries and economies, an average of just 34% of adults across participating economies reached its minimum financial-literacy target score. Its measure is different from FinAccess, so the figures should not be treated as a country ranking. They do, however, underline a shared problem: adulthood arrives with financial responsibilities whether or not we have been prepared for them. [2]
Does learning actually help? Researchers Tim Kaiser, Annamaria Lusardi, Lukas Menkhoff and Carly Urban examined 76 randomised experiments involving more than 160,000 people across 33 countries. Their analysis found that financial education improved financial knowledge and behaviour on average. This research concerns financial education generally; it does not evaluate Serrari’s webinar. It gives us a sound reason to take learning seriously, while remembering that the value of a particular session depends on its quality and what we do afterwards. [3]
Financial literacy begins with being able to look at your money without needing a motivational speech first. What comes in? What must go out? Which costs are predictable? Which debts are consuming tomorrow’s income? A workable budget makes those questions visible. It should leave room for a life you can actually live, because a plan built on permanent misery is likely to be abandoned the moment somebody suggests lunch.
It also helps us distinguish a difficult income situation from an avoidable money habit. Low pay, unemployment, illness and family responsibilities are real pressures. Nobody should be told that a notebook can magically stretch an inadequate income. Financial knowledge helps us understand the choices available within our circumstances, spot costs we can change and recognise when the bigger task is earning more or seeking support. It should replace confusion with clarity, never hardship with blame.
For a business owner, that clarity can begin with one uncomfortable discovery: the balance in the till is not all available to spend. Some belongs to suppliers, some must replace stock and some must cover running costs. A good sales day can produce a very bad week if every shilling is treated as personal income. The business may be busy while its owner is unknowingly eating next Tuesday’s inventory.
For an employee, the lesson may be that a pay rise needs a plan before it acquires new monthly commitments. For a freelancer, it may be learning to prepare for quiet periods during a busy month. For a parent, it may be setting money aside for school costs well before the term begins. Different lives require different arrangements. Everyone benefits from understanding the connection between today’s decisions and tomorrow’s obligations.
Borrowing becomes easier to assess when we look beyond the amount offered and ask about the full repayment, fees, due dates and consequences of delay. “Approved” can be an exciting word on a phone screen. It is less exciting when three repayments arrive together. A useful financial lesson teaches us to calculate whether the repayment fits the income we can reasonably expect, rather than the income we are passionately hoping for.
Then there is the confusion around investing. A money market fund pools investors’ money into a professionally managed portfolio of short-term instruments. A bond involves lending money to an issuer under stated terms. Special funds may use different assets and strategies. Understanding those distinctions helps us ask about risk, access to our money, charges and suitability before being dazzled by a percentage. Learning the vocabulary is useful because it allows us to interrogate the offer. [5]
Consider the phrase “monthly income from bonds”. It sounds straightforward until you discover that Kenyan Treasury bonds typically pay interest every six months, as CBK explains. Planning a monthly income from bonds therefore requires understanding payment dates and how the cash will be managed. An annual rate, an interest payment and money available to spend each month are different things. That is exactly the kind of detail worth understanding before you commit your savings. [4]
The same care applies to funds. A quoted return is only part of the decision. What fees apply? How long does withdrawal take? What could cause losses? Is the money needed soon? The Capital Markets Authority advises investors to read scheme documents, consider their risk appetite and investment horizon, and use licensed and approved capital-markets intermediaries. A financial-literacy session can help make those questions feel normal rather than embarrassing. [6]
And questions matter when a stranger promises unusually large, guaranteed profits, demands an immediate decision or refuses to explain how money is made. Excitement can make us hurry past the very details that deserve attention. The person who pauses to verify an offer may look less adventurous in the group chat. They may also be the person who still has their savings when the group administrator stops replying.
Now let us talk honestly about KES 750. It is meaningful money. It deserves the same deliberate consideration as any other expense. The case for spending it on financial education is that a useful lesson can influence decisions you repeat for months or years. You might use it whenever you compare a loan, plan a payment, review spending or assess an investment. Its value can continue long after the session ends.
Take a simple illustration. Suppose reviewing your spending reveals an unused service costing KES 250 a month, and you cancel it without a penalty. Over 12 months, that decision releases KES 3,000. After a KES 750 session fee, the difference is KES 2,250. This is an example, not a promised result. It shows how one modest, sustained change can be worth more than the cost of learning how to find it.
Or suppose better planning helps you avoid a chargeable late payment, or comparing the full cost of borrowing leads you to a less expensive option. The benefit depends on the actual terms and your circumstances. It can still be substantial. We often look for financial progress in a dramatic breakthrough when part of it may come from noticing, questioning and changing something we have repeated for far too long.
That is why Serrari’s session could be the smartest KES 750 you spend this year. You are allocating money to the person who makes every other decision about your finances: you. The strongest case for the fee is the possibility of better judgement across many future decisions. It becomes more compelling when you arrive with a real question and leave ready to apply what you understand.
Serrari is relevant because its published educational offering connects everyday money management with the investment landscape Kenyans encounter. Its website provides financial guides, market comparisons and calculators, while its Wealth Builder material describes a focus on money habits, investing fundamentals and risk management. The webinar’s advertised coverage gives learners a concrete reason to engage: begin making sense of the products and ideas that already appear in conversations about growing money. [8]
The Thursday schedule adds something useful: a specific appointment to learn. “I will sort out my finances” is a noble ambition with a remarkable ability to survive several birthdays unchanged. A date in the calendar gives it somewhere to begin. Free information is valuable too; a scheduled session offers a defined topic and time to concentrate. Whether you buy education or use free resources, focused attention and follow-through do much of the work.
Go into the session with a purpose. Write down one money problem you want to understand. If debt is the concern, have the repayment amounts and dates available for your own reference. If investing is the concern, identify what the money is for and when you might need it. Review the advertised session topic and bring the questions that matter to your situation. You do not need to arrive sounding like a fund manager.
Afterwards, choose one practical action. Review a recurring expense. Start separating business and personal transactions. Put a realistic amount aside for a known bill. Read the documents behind an investment you have been considering. The point is to turn understanding into a habit. A notebook full of impressive phrases will not do much if every money decision continues exactly as before.
Financial literacy matters within families too. It can make conversations about support, school fees, debt and shared goals more specific and less mysterious. Generosity becomes easier to sustain when it has a place in the budget. Children can learn from seeing adults compare prices, plan purchases and admit when something must wait. Those ordinary examples can help the next generation start with more guidance than many of us received.
Serrari’s role here is education. The KES 750 pays for a session; it is not a deposit into an investment or a promise of income. Mentioning a fund in a webinar does not make that fund suitable for every participant. The practical goal is to become better equipped to evaluate your options and seek qualified advice where your circumstances require it. That is a worthwhile ambition for anyone responsible for earning, spending, borrowing or saving. [7][8]
Registration has also become simpler. You can now register without creating an account, and a calendar invitation will be sent automatically to your email. Visit https://myserrari.serrarigroup.com/webinars and register for your chosen session. The fee is KES 750 per session, and the webinars take place every Thursday at 6:00 p.m. EAT, or 3:00 p.m. GMT. Your next step can be as concrete as putting that appointment in your week. [7]
You have already invested years in learning how to earn a living. Give some attention to understanding the money that living brings. Register with Serrari, arrive curious, and put a useful lesson to work. Your money has been attending meetings without you for long enough. This Thursday, pull up a chair.
Read Also: You Work Too Hard to Keep Starting From Zero