
Kenyan Banks: Profits Without Purpose, SMEs Without Breath

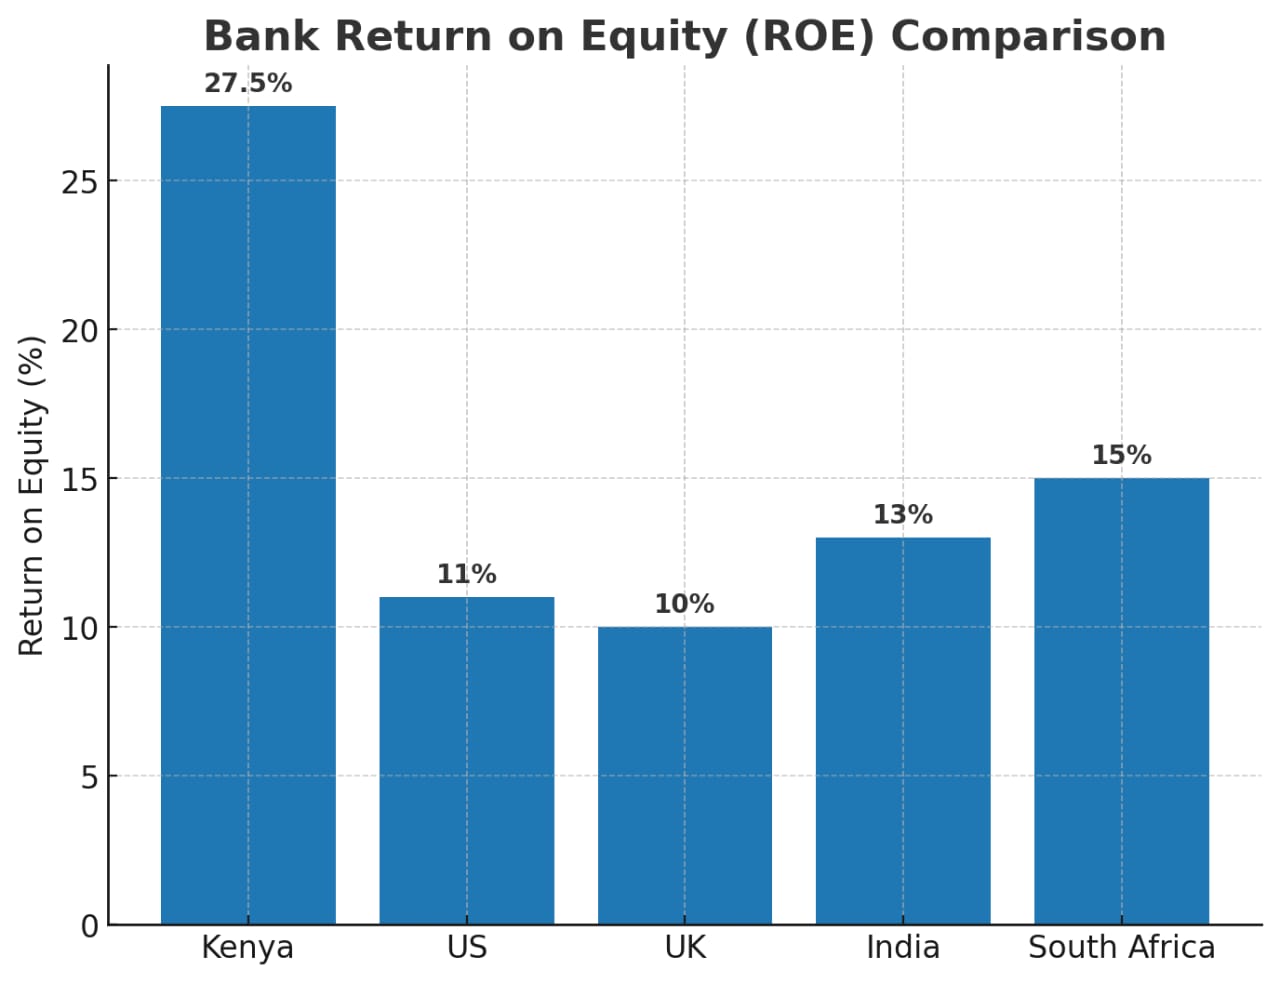
Kenya’s banking sector is celebrated in glossy reports as one of the most profitable on the continent, flaunting a return on equity that ranges between 25% and 30%. Global averages hover at 9–15%, meaning our banks outperform Wall Street, London, and Mumbai. Yet while shareholders smile, Kenyan SMEs—the engine of 80% of employment—are left suffocating without credit.
This paradox is not accidental. Banks are not miscalculating. They are making deliberate choices to pursue easy profits, abandoning the hard, messy, but vital business of financing small and medium-sized enterprises. Instead of nurturing the backbone of Kenya’s economy, banks feed off government borrowing like bloated ticks, swollen with taxpayer-funded securities.
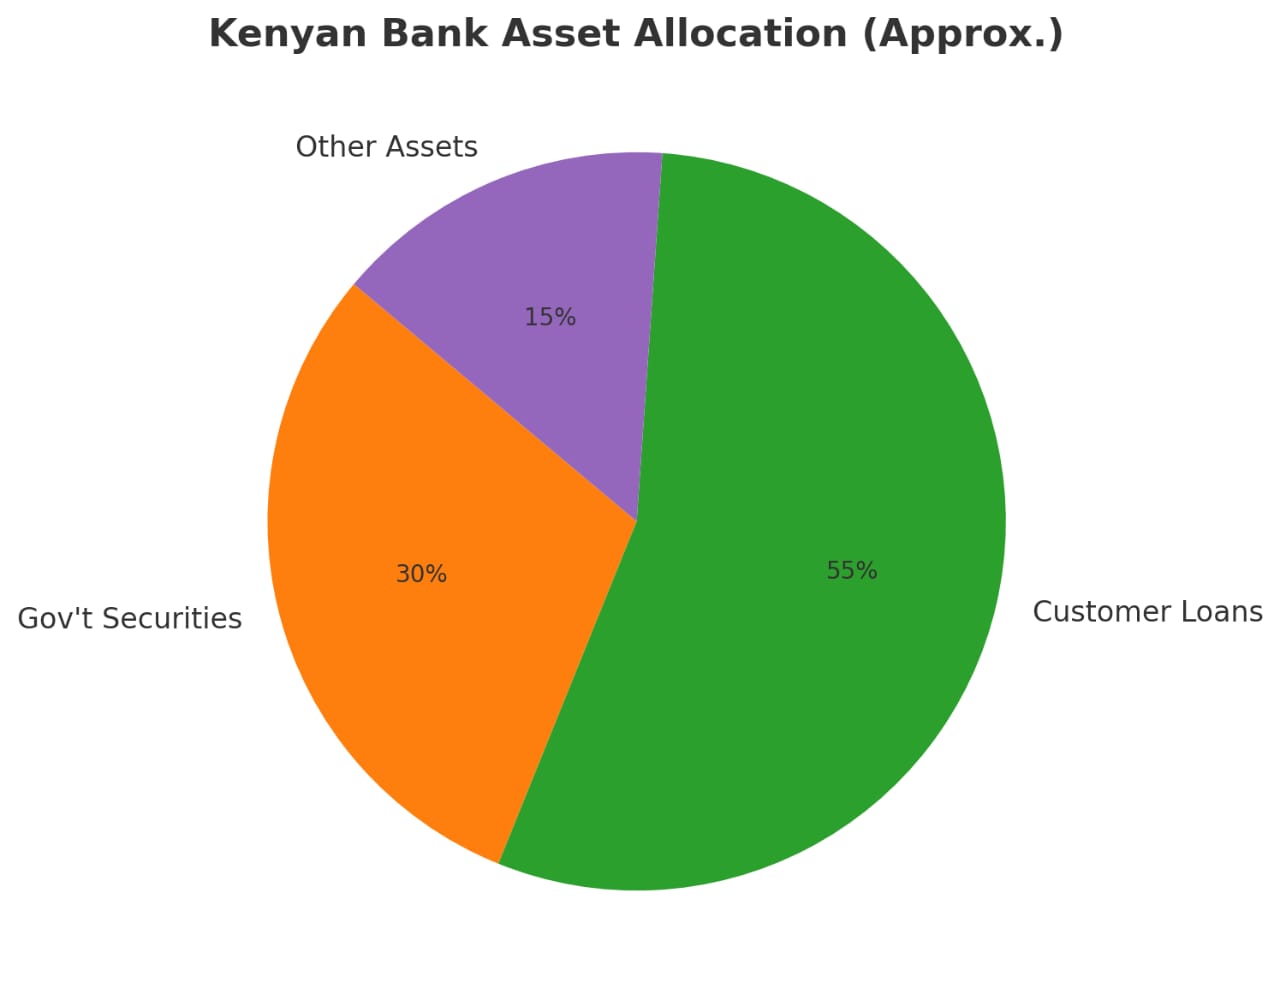
Nearly 30% of Kenyan bank assets are parked in government bonds, a lazy comfort zone yielding 12–15% risk-free returns. Why sweat to understand an SME’s business model, assess risks, and build lasting relationships, when government paper offers the illusion of stability? This addiction to treasury bills has made banks custodians of public debt rather than partners in private enterprise.
Read Also: Standard Chartered Kenya: Cracks Beneath the Shine
The cruel irony is that while banks boast their fortress balance sheets, SMEs—the hair salons, boda repair shops, manufacturers, and farmers—collapse under the weight of inaccessible financing. What was once a promise of inclusion has turned into exclusion. Credit is a fortress with locked gates, and banks hold the keys, refusing to open them.
The defenders of this banking strategy argue it’s rational: why risk defaults when the state guarantees interest? But what they ignore is the larger irrationality of an economy that eats its own tail. A government that crowds out credit leaves SMEs without fuel, leading to joblessness, reduced tax revenue, and eventually, a weaker state that may default on those same bonds.
It’s not just an economic issue; it’s a moral one. How can banks post Sh200 billion in combined profits while the youth in Gikomba can’t access a Sh50,000 loan to expand their stalls? How can bank executives build mansions in Runda while entire factories in Thika shut down for lack of working capital? The profit is soaked in the blood of opportunity denied.
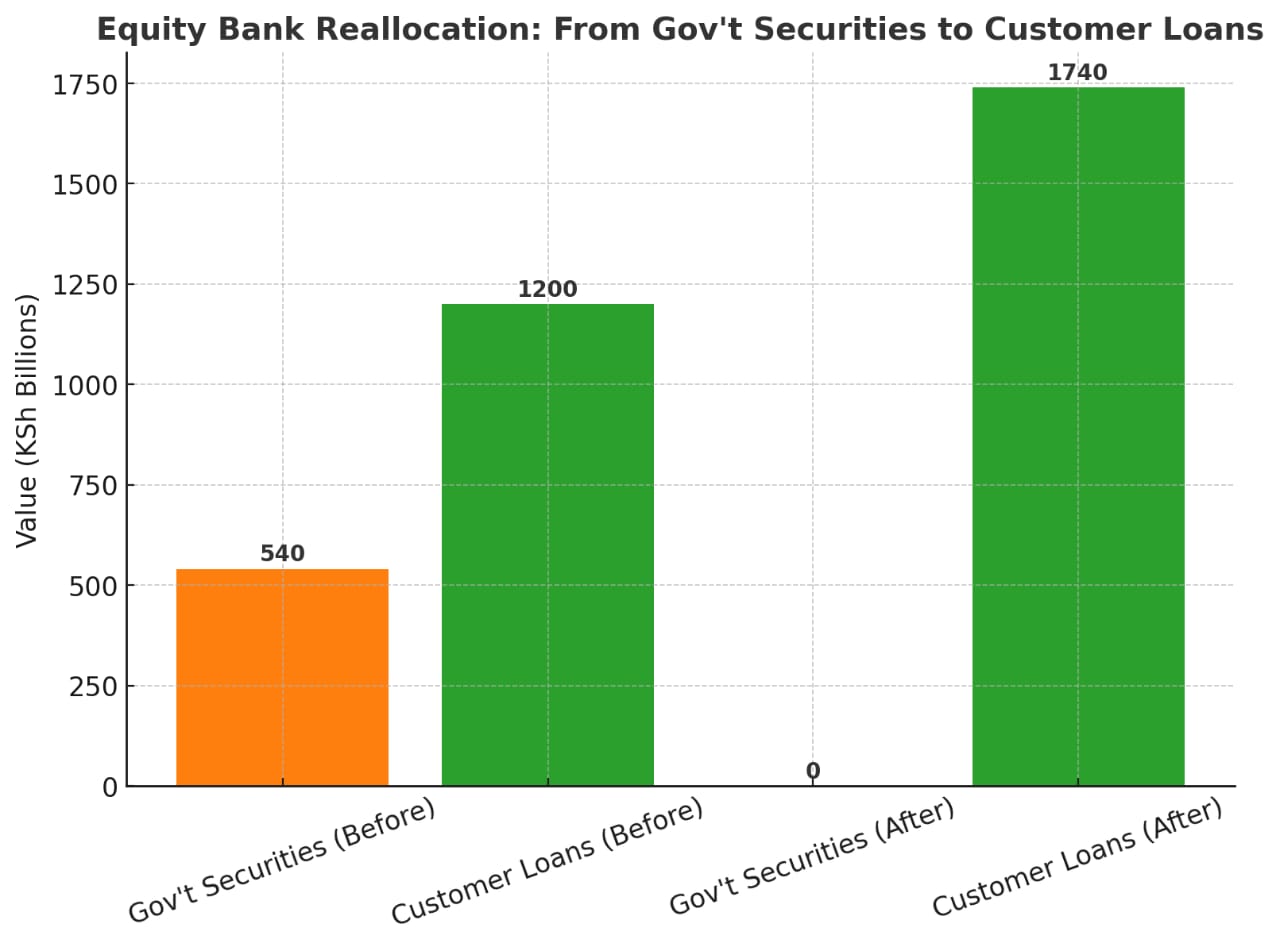
Equity Group’s recent decision to reallocate nearly KSh 540 billion from government securities back into customer loans is a rare glimmer of courage. It signals recognition that banking should serve the economy, not just cannibalize it. But this cannot be Equity alone. Without systemic change, one bold player cannot reform an industry addicted to easy money.
Safaricom adds another twist to this cruel story. Sitting on one of the richest SME data troves in Africa, it knows who earns, who spends, and who has potential. Yet it cannot lend at scale because regulation clips its wings. The result is tragic: data that could unlock trillions in SME lending sits wasted, while the government conjures political gimmicks like the Hustler Fund.
The Hustler Fund, a populist attempt to offer credit, has failed to scale with discipline or sustainability. It is politicized debt, not transformative capital. Instead of empowering hustlers, it shackles them with micro handouts while banks look the other way. It is like tossing a bucket of water on a forest fire and calling it firefighting.
Kenyan banks argue that SME lending is high risk. But risk is not static; it is managed. Banks in Asia lend to SMEs aggressively, using innovative credit scoring and partnerships. What excuse do Kenyan banks have when they have M-Pesa data, CRB data, and transaction histories at their fingertips? The risk narrative is a lazy smokescreen for complacency.
Read Also: Kenya Shilling Overnight Interbank Average Averaged 9.46% During The Week
The structural danger is obvious. Banks that tie their fortunes to government debt live or die by fiscal solvency. If Kenya defaults or restructures, those paper profits evaporate overnight. The so-called “safe play” is a mirage; it is exposure disguised as prudence. Betting on a government drowning in debt is not safe; it is slow suicide.
The human cost is invisible to balance sheets. The woman in Eldoret who cannot expand her tailoring business, the farmer in Bungoma forced to sell maize to middlemen at throwaway prices, the Nairobi start-up stu