
When the Order Is Bigger Than Your Bank Balance, It Should Not Be Bigger Than Your Business
The real business challenge is often not finding a customer. It is finding the money to serve that customer before payment arrives.
Every entrepreneur dreams of receiving a large order. The email lands, the phone rings or the local purchase order is finally issued, and for a few precious minutes the future feels wide open. Then reality walks into the room carrying a calculator. The supplier wants a deposit. Workers need wages. Packaging must be bought. Transport has to be booked. Taxes, insurance and clearing charges do not wait for the customer to pay. Suddenly, an order that should feel like a breakthrough begins to feel like a crisis.
This is the quiet working-capital problem behind many stalled Kenyan businesses. A company may be profitable on paper and still be unable to deliver because its cash is trapped elsewhere: in stock, in unpaid invoices or in equipment already serving another contract. Profit answers the question, “Is this business making money?” Cash flow answers the more urgent question, “Can this business pay for what must happen today?” A healthy business needs both.
That is why pre-shipment financing matters. In simple language, it is working capital provided before goods are shipped or an order is completed. It can help an eligible business buy inputs, manufacture or assemble products, pay for packaging, transport goods and meet other costs directly connected to fulfilling a confirmed transaction. The financing is then repaid according to agreed terms, normally from the proceeds of the trade. It is not free money, and it does not turn a weak deal into a good one. Used carefully, however, it can bridge the dangerous gap between winning business and being paid for it.
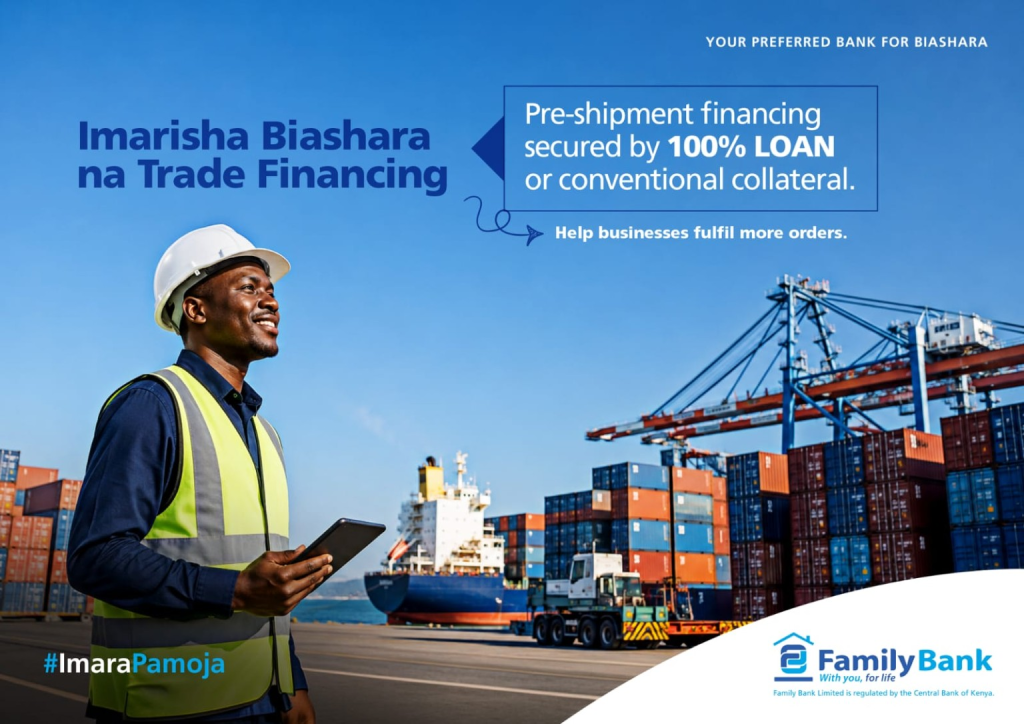
The Family Bank artwork captures this opportunity in a powerful promise: pre-shipment financing secured by a 100% loan or conventional collateral, designed to help businesses fulfil more orders. The wording is important. A “100% loan” here refers to an eligible cash-backed form of security, not a promise that every applicant will automatically receive the entire cost of an order without assessment. Conventional collateral may also be considered. The exact amount, security, pricing, documents and repayment structure remain subject to the bank’s appraisal and the specific transaction.
For an entrepreneur, the benefit is practical. Imagine a furniture maker who receives an order to supply desks to a school. The customer will pay after delivery, but timber, fittings, labour and transport must be paid for now. Without financing, the owner may reject the order, deliver late or borrow expensively from several informal sources. With well-structured pre-shipment finance, the business can purchase the required inputs, organise production and deliver within the agreed timeline. A completed order produces more than revenue: it builds credibility, preserves the customer relationship and improves the chance of winning the next contract.
The same principle applies to a grain trader buying stock for a confirmed buyer, a manufacturer producing goods for export, a contractor supplying equipment, or a distributor preparing a shipment. The facility can protect the business from draining every shilling of its own cash into one order. That matters because rent, salaries, utilities, and everyday operations continue even while a major contract is being fulfilled. Good financing does not merely fund the order; it helps keep the rest of the business alive while the order moves.
Family Bank naturally enters this conversation because its trade-finance offering goes beyond one product. Its official trade-finance information lists pre-shipment finance for working capital prior to delivery, local purchase order financing for suppliers and contractors, invoice or certificate discounting for advances against unpaid invoices, import-duty financing, post-import financing, structured trade finance, letters of credit, guarantees and bills avalisation. Different businesses face different gaps, so the right question is not simply, “Can I get a loan?” It is, “Which facility matches the exact stage of my transaction?”
If the obstacle comes before delivery, pre-shipment finance may be the relevant conversation. If goods have already been supplied and a credible invoice is awaiting payment, invoice discounting may be more suitable. If an importer needs support with port charges or supplier-payment arrangements, another trade-finance instrument may fit better. Matching the tool to the transaction prevents a business from using an expensive or poorly timed facility for the wrong purpose.
Entrepreneurs should also understand what a bank is likely to examine. A confirmed order is a beginning, not the entire case. The bank may need to establish that the buyer is genuine and able to pay, that the supplier can actually deliver, that the margins are sufficient, and that the requested financing is tied to a real commercial cycle. Business registration records, tax and compliance documents, bank statements, management accounts, contracts, quotations, invoices, purchase orders, delivery schedules and evidence of previous performance may all become important depending on the transaction.
Before signing, the entrepreneur should calculate the whole deal, not just the sales value. Start with the contract price, then subtract the cost