
Here Is The Real Reason Kenyans Skip Health Insurance And Why the Fix Isn’t What You’d Think
Ask most Kenyans why they don’t have health insurance, and you rarely hear “I don’t believe in it.” You hear something closer to: “Not this month.”
That distinction matters more than it seems. It tells you the problem isn’t awareness or attitude; it’s cash flow. And cash flow problems need cash flow solutions, not more pamphlets about the importance of cover.
A Product Everyone Agrees On, That Almost Nobody Buys On Time
I’ve sat through enough conversations with small business owners, teachers, and salaried employees to notice a pattern. Nobody argues against health insurance. Everyone nods along when you explain what a single hospital admission can do to a household’s finances. And then, almost without fail, the conversation ends with some version of: “I’ll sort it out once things are a bit more stable.”
The trouble is, “more stable” rarely arrives on schedule. Rent doesn’t wait. School fees land in January whether or not you’re ready. Business costs eat into whatever’s left. An annual insurance premium, paid as one lump sum, ends up competing with every other financial obligation a household has — and it usually loses, not because people don’t value it, but because it’s the one bill that can technically be delayed without an immediate consequence. Until it can’t.
That’s the cruelty of medical emergencies: they don’t consult your budget calendar. A routine outpatient visit turns into something that needs specialist care. A minor accident becomes a multi-day admission. And suddenly a family is liquidating savings meant for a business or a plot of land, or worse, borrowing at punishing rates just to clear a hospital bill.
Why Instalments Change the Psychology, Not Just the Math
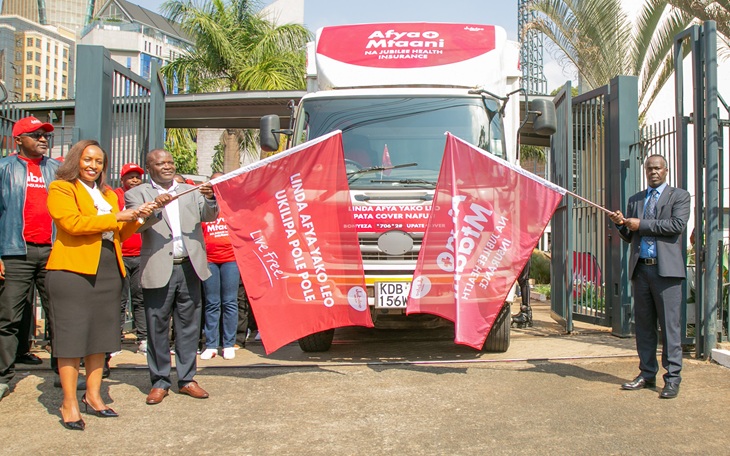
This is where flexible-payment models like Jubilee Health Insurance’s Lipa Pole Pole are worth paying attention to, not as a marketing gimmick, but as a genuinely sound response to how people actually manage money.
Spreading a premium across up to ten months doesn’t just make the number smaller. It changes the category of expense in someone’s mind. A large annual premium sits in the same mental bucket as “big, unavoidable, painful decisions” — things you delay because committing to them feels risky. A modest monthly instalment sits alongside rent, electricity, and airtime. It becomes routine rather than remarkable.
That shift is underrated. Behavioral economists have long noted that people are far more willing to commit to small, predictable, recurring payments than to a single large one, even when the total cost is identical or slightly higher. It’s not irrational, it’s a reasonable response to uncertainty. Nobody knows exactly what next month holds, but most people can estimate what they can spare each month with reasonable confidence.
Protecting the Money You’ve Already Saved
There’s a second, quieter benefit here that doesn’t get talked about enough: instalment-based health cover protects other savings goals, not just health.
Money set aside for a business expansion, a child’s university fees, or a piece of land is vulnerable precisely because it’s liquid and accessible. It’s the first-place people turn when a medical bill lands unexpectedly. Insurance, paid in a way that doesn’t require draining that fund upfront to get the cover in place, means those savings stay intact for their intended purpose. The policy becomes a buffer standing in front of your other financial goals, rather than one more goal competing against them.
The Real Cost of Waiting
It’s worth being blunt about the alternative. Going without cover doesn’t mean avoiding cost, it means deferring an unknown, potentially much larger cost to an unpredictable date. Fundraisers, emergency loans, and asset sales are not free; they’re simply expensive in ways that don’t show up as a fixed monthly figure. When you compare a predictable instalment against the actual, lived cost of an uninsured medical crisis, the math isn’t close.
A Sensible Middle Ground
None of this means instalment plans are a cure-all. People still need to understand what a policy covers, what it excludes, and whether the plan actually matches their family’s likely medical needs, that homework doesn’t go away just because the payment schedule got easier.
But as a way of closing the gap between “I know I need this” and “I actually have it,” flexible payment structures address the real bottleneck, which was never conviction. It was timing.
If cost has been the thing standing between you and cover, options like Jubilee Health Lipa Pole Pole are worth a look, not as a discount