


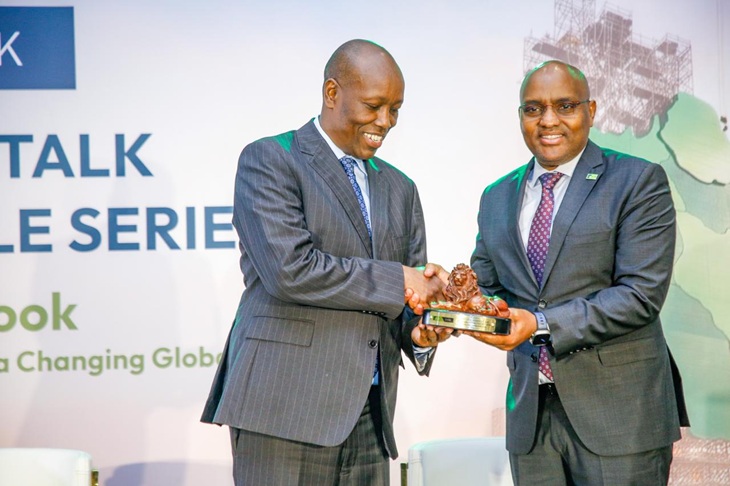
Kenya’s economic growth is expected to remain positive in 2026 and 2027, supported by a recovery in industry, resilient services and infrastructure investment, but rising global uncertainties and climate-related shocks could weigh on the outlook, according to an economic presentation delivered during the KCB Kenya Economic Outlook PowerTalk Series at the Radisson Blu Hotel in Nairobi.
KCB Kenya projects Kenya’s economy to grow by 4.5% in 2026 and 4.7% in 2027, based on International Monetary Fund (IMF) forecasts. The outlook comes against the backdrop of heightened geopolitical tensions, rising global energy prices and the expected El Niño weather conditions from October 2026.
Data presented at the forum showed that Kenya’s real gross domestic product (GDP) growth accelerated to 5.3% in the first quarter of 2026, up from 4.9% in the corresponding period in 2025. The improvement was attributed to a recovery in the industrial sector and continued resilience in services.

Construction has been a key driver of the industrial recovery, while services are expected to benefit from the continued digitisation of the economy and expansion of e-commerce. Improved credit uptake across manufacturing, building and construction, agriculture, consumer durables and trade is also expected to support economic activity.
However, the presentation warned that the economic impact of the US-Israel conflict with Iran was likely to have weakened growth in the second quarter and into the third quarter of 2026, largely through higher domestic fuel prices and weaker economic sentiment.
The conflict has heightened concerns about global energy supplies, particularly disruptions affecting commercial shipping and supply chains. For Kenya, which relies on imported petroleum products, prolonged increases in international oil prices could raise transport and production costs, feed into consumer prices and put pressure on household spending and business margins.
The outlook will partly depend on how the conflict develops. A resolution that allows energy supplies to normalise could ease inflationary pressures, while an escalation could keep oil prices elevated and complicate efforts to maintain price stability.
It outlined a potential recovery scenario in which productive negotiations could lead to a preliminary agreement by the first quarter of 2027, allowing fuel prices to decline to between US$70 and US$80 per barrel. Under a more adverse scenario, a return to high-intensity conflict could keep prices above US$90 per barrel, prolong inflationary pressures and increase the likelihood of further monetary policy tightening.
Beyond geopolitical risks, Kenya’s economic performance will also depend on domestic price trends, the exchange rate, weather conditions and the cost of borrowing.
Read Also: KCB to Discontinue Old Mobile Banking App on October 15
Inflation and interest rates remain key to business confidence
Kenya’s price outlook is expected to remain broadly stable into 2027, supported by monetary policy measures, government interventions and relative exchange-rate stability. However, the presentation noted that headline inflation had moved above the midpoint of the target range, partly because of rising fuel prices and persistently high global energy costs.
Core inflation was also reported to be rising, signalling broader price pressures that could influence monetary policy decisions.
At the same time, KCB identified appropriate monetary policy actions, government interventions such as fuel-related tax reductions and subsidies, and exchange-rate stability as important factors in containing inflation. A stable shilling helps moderate imported inflation by limiting the local-currency cost of goods and inputs purchased from abroad.
Short-term interest rates are expected to remain in single digits into 2027, supported by an accommodative monetary policy stance. Continued domestic borrowing by the government, backed by liquidity in the local market, is also expected to shape financial conditions.
For businesses, the direction of inflation and interest rates will remain important in determining the cost of working capital, investment financing and consumer credit. Lower borrowing costs could encourage investment and support demand, while renewed inflationary pressure could limit the room for further monetary easing.
The shilling has shown marginal volatility despite elevated global uncertainty, supported by remittance inflows, tourism receipts and adequate foreign exchange reserves, according to the presentation.
These inflows remain important in supporting the availability of foreign currency and helping cushion the economy against external shocks.
El Niño threatens agriculture, food prices and essential services
Climate-related risks are another major concern for Kenya and the wider East African region, with El Niño conditions expected from October 2026 potentially disrupting agricultural production, transport and the provision of essential services, including education and healthcare.
The presentation cautioned that the timing, intensity and persistence of the weather conditions would be critical in determining their economic impact.
Agriculture contributes more than 20% of regional GDP, making weather disruptions a significant threat to economic performance. Reduced agricultural output could affect farmers’ incomes, food availability and export earnings, while damage to transport networks could increase the cost of moving goods to markets.
Food and transport costs could consequently rise, adding to inflationary pressure and putting household budgets under strain. The presentation also warned that food-security buffers could be tested and that drought remained a possibility following periods of heavy rainfall.
Historical experience illustrates the potential impact. The presentation cited the 1997/98 El Niño, which slowed growth across the region, with Kenya’s economic growth falling to 1.8% in 1998 from 4.6% in 1996.
The potential disruption presents risks for businesses across agriculture, manufacturing, transport and retail, particularly those dependent on reliable supplies of raw materials, stable logistics and predictable operating costs.
East Africa’s infrastructure and trade offer growth opportunities
Despite the risks, the regional outlook points to opportunities arising from infrastructure development, trade integration and the expansion of services.
According to the presentation, East African Community economies have recorded annual GDP growth rates ranging between 5.5% and 6% over the past five years, making the region one of the fastest-growing in Sub-Saharan Africa.
Infrastructure and connectivity projects are expected to remain important growth drivers in 2026 and 2027. These include railway links such as the Standard Gauge Railway, the East African Crude Oil Pipeline, port expansion, hydropower projects and road development.
Such investments can improve regional connectivity, facilitate trade and reduce logistical constraints for businesses operating across borders.
The diversification of export commodities and markets is also expected to create opportunities. Products identified in the presentation include coffee, tea, horticultural produce, cocoa and cashew nuts, alongside minerals such as gold, copper, cobalt, tin ore and soda ash.
Expanded access to international markets, including developments involving the African Growth and Opportunity Act (AGOA), the removal of Chinese tariffs on certain African products and deeper intra-African trade, could provide additional opportunities for exporters.
Services are another area of potential growth, particularly financial services, insurance, mobile money, tourism, meetings and events, and the digital economy.
For Kenyan businesses, these developments could create opportunities to expand into neighbouring markets, diversify supply chains and develop new revenue streams. However, taking advantage of them will require attention to changing trade conditions, financing costs and operational risks.
Global interest rates and capital flows remain a concern
KCB also identified monetary policy decisions in major economies, including the United States, the euro area, Japan and the United Kingdom, as an important influence on investment decisions in emerging and developing markets.
Higher interest rates in developed economies can encourage investors to move capital towards assets offering relatively attractive returns, potentially reducing capital flows to developing markets.
Such movements can place pressure on local currencies, increase the cost of servicing foreign-denominated debt and complicate domestic monetary policy decisions.
Developing economies may respond to higher foreign interest rates by raising domestic rates to safeguard investor returns. However, the timing and extent of such responses will depend on inflationary conditions in individual markets.
For Kenya, the challenge will be to maintain macroeconomic stability while supporting economic activity, investment and access to credit.
Businesses urged to navigate uncertainty while pursuing growth
The forum highlighted a mixed environment for businesses: domestic economic activity is showing resilience, but external shocks could affect the cost of doing business and the pace of growth.
The projected expansion in construction, services, digital commerce and regional trade provides opportunities for companies seeking to grow. At the same time, geopolitical tensions, volatile energy prices, adverse weather and shifts in global interest rates remain significant risks.
Businesses will need to monitor fuel and food prices, assess exposure to exchange-rate movements, manage financing requirements and prepare for potential disruptions to supply chains. Companies operating in agriculture and transport may also need to account for weather-related interruptions and changing operating costs.
For policymakers, maintaining price stability, supporting infrastructure development and preserving confidence in the economy will be important in sustaining growth amid uncertainty.
While Kenya’s economy is expected to continue expanding through 2027, the pace and quality of that growth will depend partly on how effectively the country manages external shocks while capitalising on domestic investment and regional economic integration.
Read Also: Equity, KCB and Co-op Emerge As Top Banking Stocks As Sector Earnings Rise 17.2%