
The Price of Belonging: Why Affordable Payments Are Kenya’s Real Financial Inclusion Test
Any Kenyan who has queued at an agent to pay a withdrawal fee larger than the transaction itself knows that access and inclusion are not the same thing. You can have a bank account and still be locked out of the formal economy by the simple, grinding cost of using it. That is the uncomfortable truth Kenya’s financial sector must now confront: the next frontier of inclusion is not opening accounts; it is making the accounts worth keeping open.
Access Without Affordability Is a Hollow Victory
Kenya’s central bank and industry bodies have long celebrated the fact that over eighty percent of adults have some form of formal financial access. But dig into how that access is actually used and a different picture emerges. Millions of Kenyans hold dormant accounts, prefer to transact in cash for anything above a few hundred shillings, or route money through informal channels precisely because the formal system nickels and dimes every movement of value.
A farmer who loses forty shillings every time she withdraws her produce payment, or a boda boda rider who pays more to move his earnings than he does to fuel his motorcycle, is not experiencing inclusion. He is experiencing taxation by another name. When the cost of participating in the formal economy rivals or exceeds the value being moved, rational people opt out, and the inclusion numbers policymakers cite become statistical fiction.
The Macroeconomic Case for Cheap Money Movement
This is not simply a consumer welfare issue; it is a growth issue. Money that moves cheaply and quickly through the formal system is money that gets counted, taxed sensibly, extended as credit, and reinvested. Every shilling that stays trapped in cash because a transfer fee is too steep is a shilling that never becomes collateral for a loan, never builds a credit history, and never contributes to the velocity of money that drives GDP expansion.
Kenya’s own growth strategy, from the Bottom-Up Economic Transformation Agenda to the broader push for a cashless, formalized SME sector, depends on capital flowing freely between households, traders, and businesses. Affordable payments are the plumbing beneath that ambition. You cannot digitize an economy and simultaneously price ordinary people out of the digital rails. Cheaper transactions widen the tax base, deepen deposits within the banking system, and give the Central Bank a truer, richer picture of economic activity to inform monetary policy. In a country still wrestling with debt sustainability and a need to grow domestic revenue, that is not a minor side benefit; it is central to the fiscal story.
A Market Signal Worth Watching
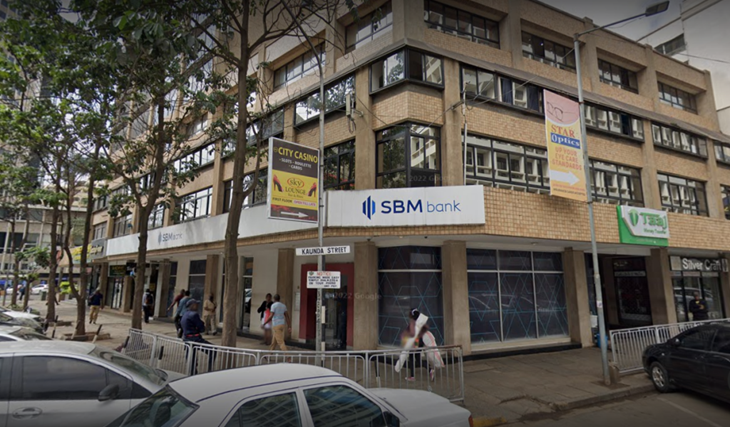
It is telling that some of the sharpest movement on pricing in 2026 has come not from regulatory pressure but from competitive necessity. SBM Bank Kenya offers a useful illustration of where the market is heading. The bank scrapped fees on PesaLink transfers conducted through its Mfukoni app and online banking, covering any amount from one shilling up to Kes 999,999, and has similarly waived charges on select ATM withdrawals, including international withdrawals on its Mastercard-branded cards. This was not charity; it was strategy, an explicit bet that a payments-led model, where the bank earns from deposits and lending rather than from clipping every transfer, builds a larger and more loyal customer base than fees ever could. The early results, reflected in the bank’s deposit growth and improved profitability, suggest the bet is paying off. Whatever one thinks of the commercial logic, the effect on ordinary users is unambiguous: money moves more freely, savings are less likely to be cannibalized by fees, and the incentive to keep funds inside the formal system grows stronger. When one institution proves that free or near-free transactions can be commercially sustainable, it puts quiet pressure on the rest of the industry to follow, which is exactly the kind of market-driven correction financial inclusion policy has struggled to engineer through regulation alone.
The truth is, Kenya does not need another awareness campaign about the virtues of digital finance; it needs a pricing environment that makes digital finance the obvious, cheaper choice. That means banks competing on transaction cost the way they once competed on interest rates, regulators continuing to press for interoperability that erodes the pricing power any single network holds over consumers, and government treating affordable payment rails as public infrastructure rather than a private profit center to be left entirely to market whims. The technology to include every Kenyan in the formal economy has existed for years. What has been missing is the will to make that inclusion affordable enough to matter. Get the pricing right, and the growth numbers will follow on their own.
Read Also: Payments Are the New Customer Experience: Why Banks Must Rethink Remittance Fees

About Soko Directory Team
Soko Directory is a Financial and Markets digital portal that tracks brands, listed firms on the NSE, SMEs and trend setters in the markets eco-system.Find us on Facebook: facebook.com/SokoDirectory and on Twitter: twitter.com/SokoDirectory