
Why More Kenyan Merchants Are Putting QR Codes At The Till
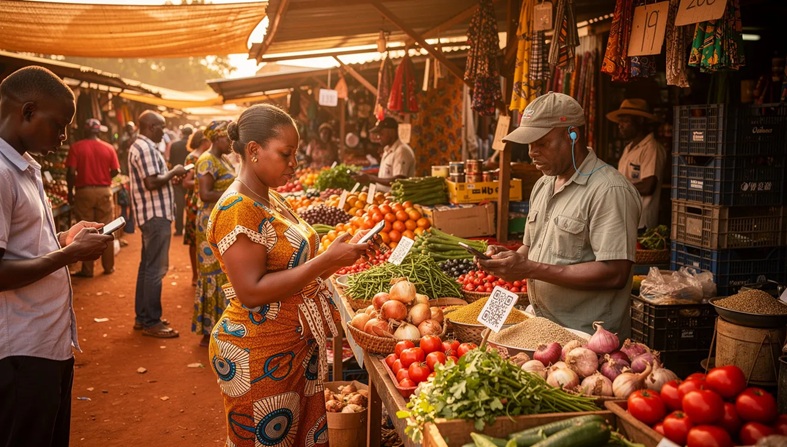
At a neighbourhood shop, a busy supermarket, a restaurant, or a petrol station, the moment of payment can determine how quickly a customer completes a transaction and moves on. For years, paying through M-PESA has involved entering a business’s Paybill or Till number, confirming the details and completing the transaction. Now, an increasingly visible alternative is emerging: scanning a QR code and paying directly from a mobile phone.
M-PESA’s rollout of its Scan to Pay service signals a shift in how Kenyan merchants and customers could interact at the point of sale. With more than 50,000 QR codes already rolled out and another 200,000 expected, the technology is moving beyond the novelty of cashless payments towards a more practical question: how can businesses make everyday transactions simpler, faster and more convenient?
The answer lies in a combination of customer experience, operational efficiency, privacy and the growing need for businesses to embrace digital tools that fit naturally into daily life.
Convenience is becoming a competitive advantage
For a merchant serving dozens or hundreds of customers daily, even small delays at the till can add up. A customer who must ask for a Till number, enter it manually, confirm the business name and complete a payment introduces several steps into what should be a straightforward transaction. The process is familiar to most Kenyans, but familiarity does not necessarily make it the most efficient option.
QR payments offer a simpler alternative. A customer scans the code displayed at the counter, follows the payment prompts and completes the transaction. By reducing the need to type payment details manually, the process can help minimise errors and make checkout more convenient.
Consider a busy lunch-hour restaurant in Nairobi’s central business district. Customers want to pay and return to work, while staff need to clear tables and serve the next group. A quicker payment process can help reduce congestion at the counter and improve the overall customer experience.
The same principle applies to supermarkets, pharmacies, salons, hardware shops and small retailers. No single transaction may save a significant amount of time, but the cumulative effect can matter to businesses processing payments throughout the day.
However, the real benefit will depend on how smoothly customers can scan, authorise and complete payments, as well as the reliability of connectivity and the payment service itself.
Privacy matters more than many customers realise
Data privacy is another important consideration in the evolution of digital payments. Kenyan consumers have become accustomed to showing payment confirmation messages to attendants, cashiers and other service providers. In some situations, a customer may turn their phone towards a stranger to demonstrate that a transaction has gone through.
That simple gesture can expose more information than necessary. Depending on the payment message and what is visible on the screen, it may reveal a customer’s name, phone number, transaction amount or other details associated with the payment.
A QR-based payment process could help reduce the need for such exchanges, particularly where the merchant can independently confirm receipt of the payment through the appropriate merchant system. Instead of relying on a customer to display a personal message, the business can use its own payment confirmation process.
This distinction is important. Customers should not have to disclose unnecessary personal information simply to prove that they have paid for a meal, purchased groceries or bought household supplies.
Nevertheless, scanning a QR code does not automatically guarantee greater privacy. The actual protection depends on how the service handles customer information, what details appear during the transaction and how merchants verify payment. Customers should also avoid sharing their mobile money PINs or approving transactions they do not recognise.
The broader opportunity is to make privacy a natural part of payment design rather than leaving customers to manage it themselves.
Fewer manual steps can mean fewer payment errors
Typing a Till number or Paybill account incorrectly can cause unnecessary complications. A customer may send money to the wrong destination, enter an incorrect account reference or have to repeat the process after discovering an error.
A QR code can reduce these risks by encoding payment information that would otherwise need to be entered manually. When implemented correctly, it helps customers initiate a payment using the details associated with the displayed code.
For merchants, fewer errors can mean less time spent resolving payment disputes, checking transaction messages and helping customers repeat failed transactions.
This matters particularly for small businesses, where the owner may be responsible for sales, stock management, customer service and financial reconciliation at the same time. Every avoidable interruption takes attention away from running the business.
That said, QR payments do not eliminate mistakes altogether. Customers still need to verify the merchant’s name and transaction amount before authorising a payment, while merchants must ensure that the codes displayed at their premises are genuine and have not been replaced or tampered with.
The benefits extend beyond the customer
The discussion around digital payments often focuses on convenience for consumers. Yet merchants stand to gain considerably when payment processes become more efficient.