
Kenya Earns It, Congo Catches Up: Inside Equity Group’s Ksh 70 Billion Quarter
Equity Group’s banking business earned Ksh 70.1 billion after tax in the nine months to September 2026, up 32% on last year. That is roughly Ksh 256 million of profit every single day.
The headline is impressive. The more interesting story is where that money comes from. Six countries, six very different banks, and one fact that would have sounded far-fetched a few years ago: the Congolese bank is now a heavyweight in its own right.
Here is the split in one sentence. Kenya brings in 58 cents of every shilling of profit, DR Congo brings in 26, and Rwanda, Uganda, Tanzania and South Sudan together make up the last 16.
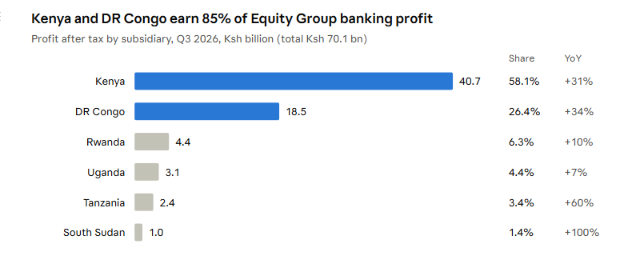
The two smallest bars are growing fastest. Tanzania’s profit rose 60% and South Sudan’s doubled, from a small base.
Kenya: the engine runs hotter
Equity Bank Kenya contributed Ksh 40.7 billion of the group’s profit after tax, up 31% from Ksh 31.07 billion. That is 58.1% of banking profit, from a business that holds only about 46% of the group’s deposits, loans and assets.
In other words, Kenya earns more than its weight. Each shilling of its balance sheet works harder than the group average.
Why profit grew faster than revenue. Total revenue rose 17% to Ksh 93.9 billion, but profit before tax jumped 30% to Ksh 45.9 billion. Three things opened that gap:
- Cheaper money. Cost of funds fell from 4.1% to 3.0%, while the yield on interest-earning assets barely moved (12.2% to 11.9%). The bank kept most of its lending income and paid savers less for deposits.
- A fatter margin. Net interest margin widened from 8.1% to 8.9%, and net interest income climbed 17% to Ksh 62.6 billion.
- Costs kept in check. Operating costs rose 11% to Ksh 41.5 billion, well behind revenue growth. That puts Kenya’s cost-to-income ratio at about 44%.
Non-funded income (fees, FX, transactions) also grew 18% to Ksh 31.3 billion. It now makes up a third of Kenya’s revenue, a useful cushion if interest rates fall further.
The result is an exceptional return. Return on average equity hit 35.2%, and return on assets rose to 5.1% from 4.2%. Few large banks anywhere earn that much on shareholders’ money.
The one thing to note: the balance sheet grew slower than profit. Assets were up 7% to Ksh 1.049 trillion, deposits up 10% and loans up 12%. Kenya is squeezing more out of what it has, more than it is growing it. NPL coverage improved to 65% from 60%, though it remains below DR Congo’s level.
DR Congo: the challenger closes in
Equity BCDC earned Ksh 18.5 billion after tax, up 34% from Ksh 13.81 billion, and supplied 26.4% of group banking profit. It grew faster than Kenya on almost every line.
The balance sheet is where the story gets striking:
| Measure | Kenya | DR Congo | DRC as % of Kenya |
|---|---|---|---|
| Total assets | Ksh 1,049 bn (+7%) | Ksh 848.2 bn (+34%) | 81% |
| Deposits | Ksh 816.6 bn (+10%) | Ksh 670.3 bn (+38%) | 82% |
| Loans | Ksh 455.2 bn (+12%) | Ksh 375.1 bn (+24%) | 82% |
| Profit after tax | Ksh 40.7 bn (+31%) | Ksh 18.5 bn (+34%) | 45% |
BCDC’s balance sheet is now more than four-fifths the size of Kenya’s. If both kept this year’s growth rates, the Congolese bank would hold more deposits and assets than the Kenyan one within about a year. That is a big “if”: growth measured in shillings also reflects currency moves, and a 38% deposit surge rarely repeats on cue. But the direction is clear.
Size isn’t yet the same as profitability. The last row of the table shows the gap. DR Congo has 81% of Kenya’s assets but earns only 45% of its profit. BCDC’s return on equity is a healthy 22.7%, but well short of Kenya’s 35.2%.
The ratios show why, and they flag what to watch:
- Margins are thinning. Net interest margin fell from 6.9% to 5.9%, and asset yield fell from 8.5% to 7.5%, while cost of funds stayed flat at 1.6%.
- Deposits are outrunning lending. Deposits grew 38% but loans only 24%, so the loan-to-deposit ratio slipped from 62% to 56%. Much of that new cash is sitting in lower-yielding assets.
- Thinner cushion for bad loans. NPL coverage dropped from 100% to 83%.
Even so, profit before tax rose 49% to Ksh 26.4 billion, and return on assets edged up to 3.2%. If BCDC can lend out more of its deposit pile at decent rates, its profit share has plenty of room to grow.
The other four: a sprinter, two steady hands and a long shot
Rwanda, Uganda, Tanzania and South Sudan together earned about Ksh 10.9 billion, or 15.5% of group profit. Their stories could hardly be more different.