
How SIB Guided Family Bank’s Decade-Long Turnaround To The NSE

On 23 June 2026, Family Bank is scheduled to cross one of the most consequential thresholds in its four-decade history. Up to 1,662,654,760 ordinary shares will be admitted to the Main Investment Market Segment of the Nairobi Securities Exchange at an introduction price of KES 18 per share, placing an opening reference value of about KES 29.9 billion on the lender. The moment deserves precision: this is not an initial public offering and no fresh capital is being raised through the listing itself. It is a Listing by Introduction, a transaction that takes shares already in existence and moves them into a regulated, visible and continuously tradable public market.
That distinction does not make the transaction less important. It makes its purpose clearer. For years, Family Bank’s shares have changed hands away from the main exchange, where finding a buyer, agreeing a price and completing a transfer could be slower and less transparent. Once the shares begin trading on the NSE, existing shareholders gain a recognised route to liquidity, prospective investors gain a more accessible entry point, and the bank gains something that every serious institution eventually needs: a public mechanism through which the market can express, day after day, what it believes the business is worth.
At the centre of that transition is Standard Investment Bank Limited, the Transaction Advisor. SIB’s task is not ceremonial and it is not simply to escort Family Bank to the bell-ringing moment. A listing by introduction requires the careful alignment of shareholder approvals, regulatory requirements, valuation work, disclosures, legal documentation, reporting-accountant inputs, share dematerialisation, market-readiness processes and communication to investors. The transaction advisor is the institution that keeps those moving parts attached to one timetable and one standard of accountability.
That is why SIB’s appointment matters. Family Bank is placing a defining corporate transition in the hands of an investment bank with more than three decades in Kenya’s capital markets and a corporate-finance record spanning more than 60 mandates valued at over KES 270 billion. SIB has worked on transactions that helped build the architecture of the market itself, including the KenGen rights issue, the Kenya Re public offer, the Nairobi Securities Exchange’s demutualisation and listing, Kenya Power’s balance-sheet restructuring and the privatisation of KWAL Holdings. These are not merely names on a credentials page. They represent experience in coordinating regulators, boards, shareholders, lawyers, accountants, brokers and investors when the cost of error is measured in both money and institutional trust.
The relationship with Family Bank also has history. In 2014, SIB served as a Joint Lead Transaction Advisor on Family Bank’s KES 3.1 billion private rights issue, helping the lender value the business and raise growth capital from shareholders. Twelve years later, SIB is again alongside the bank, but the assignment has evolved. The earlier mandate helped strengthen the balance sheet; the current one helps establish a public market for the ownership of that balance sheet. It is a progression from raising capital inside a relatively closed shareholder structure to opening the bank’s value to wider scrutiny, liquidity and price discovery.
Read Also: Family Bank’s Profits Up 55.4% For The Year 2025
Family Bank does not arrive at this point as a speculative promise. It arrives carrying the evidence of a difficult but increasingly convincing financial recovery. In 2016, the Group reported KES 352 million in profit after tax. A year later it fell into a KES 1.00 billion loss, a trough that could have defined the institution had management failed to rebuild earnings, strengthen controls and restore confidence. Instead, profit returned to KES 244 million in 2018, rose to KES 950 million in 2019 and reached KES 1.16 billion in 2020. The decisive break came in 2021, when Group profit after tax moved above KES 2.3 billion.
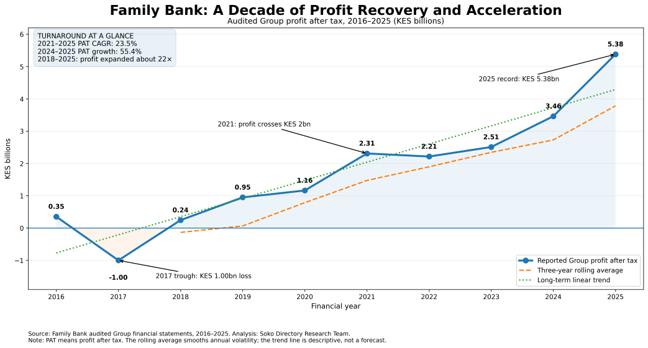
The line is not perfectly smooth, and that is precisely why it is credible. Profit softened slightly to KES 2.21 billion in 2022 before recovering to KES 2.51 billion in 2023, climbing to KES 3.46 billion in 2024 and then accelerating to KES 5.38 billion in 2025. Between 2021 and 2025, Group profit after tax grew at a compound annual rate of about 23.5 per cent. The 2025 result alone was approximately 55 per cent above the previous year. Measured from the fragile recovery recorded in 2018, annual profit expanded about twenty-two times by 2025.
Behind those earnings is an institution with the scale to belong on the NSE’s main market. By the end of 2025, Family Bank had total assets of KES 208.7 billion, shareholders’ funds of KES 32.6 billion, more than 1.3 million customers and 96 branches spread across 32 counties. The bank’s 2025 private placement also raised KES 8 billion against a KES 6.09 billion target, an outcome that indicates substantial shareholder appetite before the shares reached the public exchange. The first quarter of 2026 added further momentum, with total assets rising to KES 230.2 billion, customer deposits reaching KES 168.9 billion and profit after tax growing to KES 1.65 billion.
These numbers do not eliminate risk, nor should a serious market article pretend that they do. Banking remains exposed to credit quality, interest-rate movements, regulation, capital requirements, competition and the health of the wider economy. A strong historical profit curve is not a guarantee of future returns. What the record does provide is a stronger basis for valuation. Investors will not be asked to price only an ambition; they will be able to examine a bank that has survived a loss-making period, rebuilt profitability, expanded its capital base and entered the market with a clearer growth strategy.
The announced KES 18 introduction price is therefore best understood as the opening reference point, not the final word on Family Bank’s value. Once trading begins, price will be shaped by the interaction of buyers and sellers, the quality and consistency of future earnings, dividend expectations, asset quality, governance, liquidity, market sentiment and confidence in management. That public contest of opinions is one of the market’s most useful disciplines. It does not produce an infallible ‘true price’, but it creates a more observable market-clearing price than an illiquid over-the-counter environment can ordinarily provide.